Home / Divisions / Mortgage & Finance
Division 02 · Mortgage & Commercial Finance

Lending arranged by a broker who has already read the numbers.

Business acquisitions, goodwill, commercial property, fit-outs, refinances and your own home loan — sourced from a panel of more than 60 banks and lenders, and submitted in a form that answers the credit team’s questions before they are asked.

Lending we arrange

From your first business loan to the building you trade from.

Residential and commercial lending, arranged around the business that is ultimately servicing it.

01

Business acquisition & goodwill lending

Buying a pharmacy, practice or trading business is a cashflow-first lending decision. We prepare a submission that presents normalised earnings, add-backs and lease position the way a credit analyst needs to see them.

  • Pharmacy and practice purchases
  • Partner buy-ins and buy-outs
  • Working capital and stock funding
  • Vendor finance coordination
02

Commercial property finance

Buying the premises you trade from, or a commercial investment, with the loan structured around the tenant, the lease and the entity that will own it.

  • Owner-occupied premises
  • Commercial investment property
  • Lease-back arrangements
  • Construction and development
03

Fit-out & equipment funding

Refits, dispensary automation, clinical and practice equipment, vehicles and technology funded with the right product — chattel mortgage, lease or term loan — for the tax position.

  • Shop and practice fit-outs
  • Robotics and clinical equipment
  • Vehicle and asset finance
  • Technology and systems
04

Refinance & restructure

Facilities reviewed against current pricing, covenants and your plans. Sometimes the answer is a new lender; often it is a better structure with the one you have.

  • Rate and fee review
  • Debt consolidation across entities
  • Covenant and security restructure
  • Releasing equity for growth
05

Home loans

Your own home loan arranged by the broker who already understands your business income — which matters when your income comes through a trust, a company or a recent acquisition.

  • Purchase and refinance
  • Self-employed and business-owner income
  • Construction and renovation
  • Bridging and relocation
06

Investment & SMSF lending

Residential investment loans structured for tax deductibility and portfolio growth. SMSF borrowing for commercial property is coordinated with Hedley Capital and your accountant — the 2026 tax reforms prohibit SMSFs from borrowing to buy residential property.

  • Investment property loans
  • Portfolio restructures
  • SMSF commercial property lending
  • Offset and split-loan structuring
Our approach

Most applications stall on things that were fixable months earlier.

Lenders rarely decline a well-run business because of its headline numbers. They decline, delay or shrink the loan because of what sits further down the file — a lease shorter than the loan term, add-backs without evidence, ATO arrears that were not disclosed, or a borrowing structure that does not fit the rules of the sector.

Because our broking sits alongside the firm’s accountants and advisers, those issues are found and fixed before a submission goes anywhere. The difference is usually weeks of credit assessment, and sometimes the difference between an approval and a decline.

  • A panel of more than 60 banks and lenders
  • Submissions prepared with your financials already reviewed by the firm
  • Business, commercial and personal lending handled by one broker
  • Best Interests Duty applies to every recommendation
How an engagement works

From first conversation to settlement.

A clear process, with every fee and commission disclosed to you in writing before anything is lodged.

Lending review

We look at what you want to achieve, your current facilities and the documents a lender will ask for.

Strategy & lender selection

We compare suitable lenders and products, and explain the trade-offs in plain language.

Submission

A complete, documented application — with the credit analyst’s likely questions already answered.

Approval to settlement

We manage valuations, conditions, documents and settlement, then review the facility as your plans change.

Who it’s for

Lending for people whose income is not a simple payslip.

Business owners, pharmacists, practitioners, investors and families with income through trusts and companies — the files that benefit most from a broker who understands accounts.

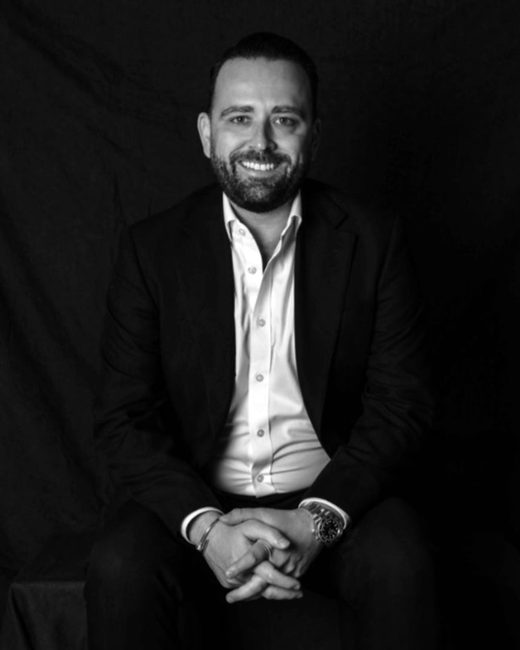
Blake Hedley, Managing Director · Property & Finance, Hedley Partners
Blake Hedley
Managing Director · Property & Finance

17+ years in finance and property, with a Bachelor of Commerce and Law and a Master of Property. Blake leads lending and premises strategy, is a senior auctioneer, and is the authorised representative behind Hedley Capital.

Common questions

Questions about lending

We may receive commission from the lender you choose, generally between 0.60% and 0.75% of the loan amount, and your credit representative may charge a fee. Any fee and the commission are disclosed to you in writing before any application is lodged. Full details are in our Credit Guide.

Often, yes. A decline usually reflects how a file was presented or one specific issue, not your whole position. We will tell you honestly what caused it and whether a different lender or structure is likely to help.

As early as possible — ideally before you are looking at a specific business. Equity, deposit sources, the borrowing structure and any existing debt all take time to get right, and good businesses do not wait for buyers to get organised.

No. We arrange home loans, investment lending, refinances and SMSF borrowing as well. Many clients find it simpler to have every facility with one broker who understands how they connect.

No. It is general information only. Any recommendation is made after we understand your circumstances and assess whether a product is not unsuitable for you, as required under the National Consumer Credit Protection Act 2009.

Resources

Read before you decide.

Credit assistance is provided by Blake Hedley as credit representative no. 555666 of LMG Broker Services Pty Ltd ACN 632 405 504, Australian Credit Licence 517192. Information about credit products is general and is not an offer of credit; any application is subject to the lender’s assessment and criteria. Full details: Licensing & disclosures.

Know where you stand before the bank tells you.

A free lending review: your current facilities, your plans, and an honest view of what a lender is likely to say.